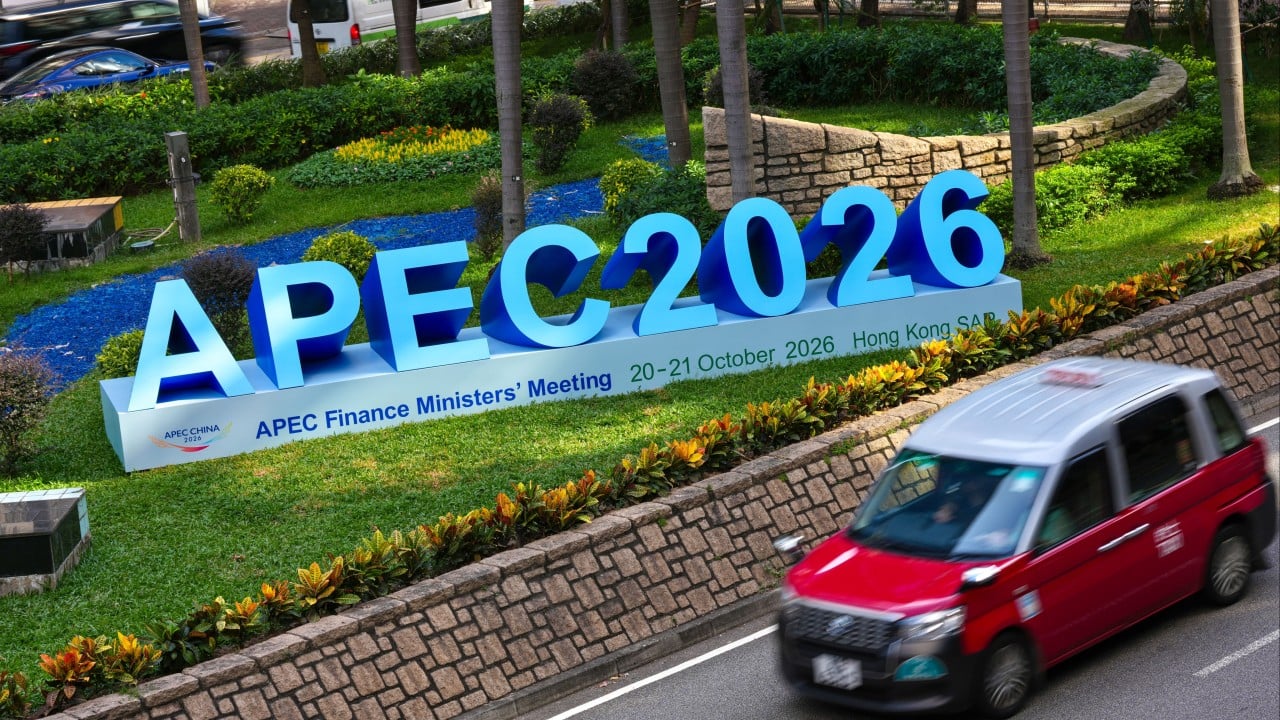
The convergence of senior fiscal leadership in special administrative regions functions less as a diplomatic exchange and more as a high-frequency economic signal. When China's finance minister delivers the opening address at an Asia-Pacific Economic Cooperation gathering in Hong Kong, the underlying mechanics involve calibrating market expectations, managing sovereign debt spreads, and signalling liquidity tolerance to offshore institutional investors. Analyzing this address requires stripping away standard diplomatic rhetoric to isolate the structural transmission channels between Beijing's fiscal policy adjustments and the liquidity conditions of international capital markets.
The Liquidity Transmission Mechanism
Cross-border fiscal addresses by sovereign finance ministers operate primarily as monetary and regulatory calibration instruments. Unlike central bank rate announcements, which target short-term interbank lending rates directly, ministerial speeches at multilateral forums establish the broad boundaries of fiscal stimulus, structural deficit tolerances, and asset allocation priorities.
When a major sovereign economy addresses an international financial hub like Hong Kong, the transmission mechanism relies on three distinct vectors:
- Offshore Bond Pricing: Institutional investors price sovereign and quasi-sovereign yields based on anticipated issuance volume and secondary market backstops. Ministerial guidance on fiscal expansion alters the duration risk premium demanded by offshore capital.
- Foreign Direct Investment Guardrails: Clarity on industrial policy subsidies and cross-border capital controls dictates the net present value calculations of multinational corporations operating within the regional trade nexus.
- Currency Stabilization Thresholds: Fiscal expansion heavily influences current account balances and capital flight vectors, forcing currency managers to balance domestic stimulus against foreign exchange volatility.
Without quantitative precision in the ministerial text, markets substitute missing data points with worst-case or best-case extrapolation models. Consequently, the primary analytical task is measuring the divergence between stated fiscal intent and historical execution capacity.
Structural Constraints on Regional Capital Allocation
The positioning of Hong Kong as the venue for mainland fiscal addresses highlights a deliberate structural arbitrage. Hong Kong functions as the primary conduit for inbound foreign capital and outbound direct investment for the mainland economy. However, the operational efficiency of this conduit depends on predictable regulatory interfaces and clear liquidity backstops.
The current economic environment presents a distinct structural constraint. Domestic balance sheet repair—specifically within local government financing vehicles and the property sector—demands sustained fiscal absorption. At the same time, regional trade fragmentation requires maintaining external competitiveness through targeted industrial subsidies.
Domestic Balance Sheet Strain
       │
       ▼
Fiscal Absorption Priority ──► Reduced Discretionary Capital
       │
       ▼
External Subsidy Trade-offs ──► Heightened Capital Selectivity
This dual mandate creates a zero-sum allocation dilemma. Every unit of liquidity deployed toward domestic debt restructuring is a unit withheld from regional liquidity injections or cross-border asset stabilization.
Market Pricing of Fiscal Ambiguity
When financial markets digest high-level policy speeches, they execute a rapid risk-pricing sequence. Ambiguity regarding structural reforms or debt resolution timelines introduces a volatility premium. Institutional portfolios adjust asset allocation weights across three horizons:
- Short-Term Tactical Rebalancing: Immediate adjustments to equity beta and currency hedges based on the tone of regulatory oversight.
- Medium-Term Structural Positioning: Sector-specific overweighting or underweighting determined by explicit subsidy allocations rather than broad market indices.
- Long-Term Sovereign Risk Assessment: Re-evaluating long-duration debt instruments based on the trajectory of debt-to-GDP ratios and nominal growth rates.
The efficiency of this pricing mechanism depends entirely on the granularity of the metrics provided in the address. Vague commitments to macroeconomic stability force markets to rely on proxy indicators, such as daily interbank repo rates, local land auction yields, and trade-weighted exchange rate indices.
Strategic Asset Allocation Under Policy Uncertainty
For institutional allocators, navigating systemic fiscal addresses requires shifting focus away from headline announcements toward execution-tracking frameworks. Because ministerial speeches inherently prioritize macro-level consensus over micro-level certainty, operational decisions must be anchored in verifiable balance sheet data rather than rhetorical intent.
The optimal strategy involves three analytical steps:
- Isolate sectors directly tied to structural fiscal guarantees from those dependent on discretionary consumer demand.
- Monitor offshore-onshore yield spreads to gauge actual capital restrictions versus stated openness.
- Maintain tactical liquidity buffers to exploit market dislocations caused by the misinterpretation of diplomatic policy framing.
Execution success is defined by recognizing that ministerial addresses do not alter economic fundamentals; they merely accelerate or delay the market's recognition of existing structural realities.